
Loans in REDA
In REDA, a loan is not its own record type with its own tab — a loan is a Lending deal. It lives on the same Opportunities tab as your leases, sales, and acquisitions, marked as the Lending kind of deal, and everything about servicing that loan hangs off it: the terms, the balances, the payments you record, and the tickets that move money in and out. This article is the map of that record. By the end you'll know where loans come from, what each stage means, how the terms and balance fields are organized, how parent and child loans fit together — and, just as importantly, the honest boundary of what REDA does and does not calculate for you. No prior REDA experience is assumed.
Access you'll need. Creating and servicing loans requires the REDA - Property Lending User permission set. Read-only sets — such as REDA - Master Data - Read Only — can view a loan but not change it.
The loan is a deal
REDA models every commercial relationship — a lease, a sale, an acquisition, a loan — as one kind of record: a deal, shown on the Opportunities tab. A loan is the Lending kind of deal. There is no separate "loan object" to learn; if you can open a deal, you can open a loan.
Practically, that means a loan comes with the machinery every deal has. It advances through a fixed set of Stages, shown as a Path across the top of the record. It carries related lists — the two that matter for lending are Loan Payments (the money you record moving on the loan) and Tickets (the short checklists that disburse funds or pay the loan off). And it rolls its numbers up to the property it's secured against. Servicing a loan, then, is really three things working together: the deal itself, its Loan Payment rows, and its Loan Disbursement / Loan Payoff tickets.
Where loans come from
A loan record reaches your Opportunities tab in one of three ways.
TBD, opened at Prospecting, with the acquisition's buying account as the borrower. It's a starting stub for the financing you expect to arrange, not a bug. See Acquisitions in REDA.When a placeholder appears, you don't delete it and start over — you fill it in. Set the real lender, the Loan Amount, and the terms, and work it forward through the stages below.
The loan lifecycle
A loan moves through six stages on its Path. You drive these by hand; unlike a lease, a loan's stages are not pushed by tickets. The working order runs from sourcing, through funding, to being retired or lost.
Prospecting → Pending → Funded → Closed Won → Payoff Pending → Closed Lost
The one surprise in that order is that Closed Won comes before Payoff Pending. In lending, "won" means the loan was successfully funded and placed — not that it's been repaid. A loan is marked Closed Won once the money is in and the deal is done, and only later moves to Payoff Pending as the principal is worked down toward settlement or refinance.
| Stage | What it means | Active? |
|---|---|---|
Prospecting (default) | Sourcing and structuring; the auto-created TBD placeholder starts here | No |
Pending | Terms agreed, awaiting funding | No |
Funded | Money is in — servicing begins | Yes |
Closed Won | Funded and successfully placed — kept on the books | Yes |
Payoff Pending | The loan is being retired (a refinance or settlement is underway) | Yes |
Closed Lost | Never funded or abandoned | No |
"Active" is the word to watch. A loan counts in a property's debt totals — and in a parent loan's or acquisition's rollups — only while it is active, which means Funded, Closed Won, or Payoff Pending. A loan sitting at Prospecting or Pending is still just a plan and does not yet move any totals. Note too that Closed Won still counts as active: a placed loan keeps contributing to the property picture unless you deliberately set it to a stage that doesn't.
Closed Won. Until then, record money with Loan Payment rows. The ticket flows are covered in Disbursements & Payoffs.
Anatomy of the loan record
Open a loan and you're looking at four groups of information: who's involved, what secures it, the terms of the agreement, and the running balances. Here's how to read each.
The single most important field is Loan Amount — the principal. It's the ceiling REDA measures everything else against: the amount you can disburse, the principal you can receive, and the amount you can allot to child loans are all capped by it, and it's what rolls up to the property's Total Loan Amount.
What REDA does not do
This is the part that saves the most confusion, so we'll state it plainly.
The only automation on the loan is bookkeeping: REDA stamps region details and rolls up the totals from the payments and tickets you enter. It does not do the loan math for you. So each instalment — its principal portion and its interest portion — is a figure you calculate and enter as a Loan Payment row. The step-by-step is in Recording Loan Payments, and the schedule-level view is in The Loan Repayment Schedule.
If you've seen a note elsewhere suggesting the terms "drive a payment schedule," treat it as out of date. The behavior described here is the verified reality of the current release.
Parent and child loans
A single facility can be split into pieces. A loan can sit beneath a parent loan — another Lending deal — so that one large credit line is divided across several properties or purposes. The structure is a single level deep: a loan can have a parent, but a parent cannot itself have a parent.
Child loans use a special value in the Loan Type field: Allocation. That value is reserved for children — try to set it on a loan that has no parent and REDA stops you:
On the parent, the Loan Allotted Amount field shows how much of the facility has been carved out to its active children — REDA sums it for you; you don't type it. And you can't over-commit: the allotted total is capped below the parent's Loan Amount.
Building and allocating a facility is covered in full in Loan Terms & Allocation.
Worked example: Meridian's Harbour Tower loan
Meridian Capital acquires Harbour Tower. As soon as the acquisition creates the property, a placeholder loan named TBD appears at Prospecting, with Meridian Capital as the borrower. The team fills it in as the real deal: lender account Harbour Capital Partners, Loan Amount 500,000.00, Loan Type Private, Amortize Interest Only, Frequency Monthly, Interest Rate 9.000%, Interest Accrual Type Arrears, and a Loan Start Date of 1 Aug — linked to the acquisition so the borrower and property match it.
Because the loan is linked to the acquisition, REDA enforces two consistency checks. If the borrower doesn't match the acquisition's buying account, or the property doesn't match, you'll see:
"Property must be same as on Acquisition Opportunity."
At this point every balance field on the loan reads zero — nothing has moved yet. When the funds arrive, the team sets the stage to Funded, and servicing begins: from here, the balances change only as Loan Payment rows and disbursement tickets are recorded. Once the placement is confirmed the team marks it Closed Won — which is also the point at which disbursement and payoff tickets become available — and, much later, moves it to Payoff Pending when the loan is being retired.
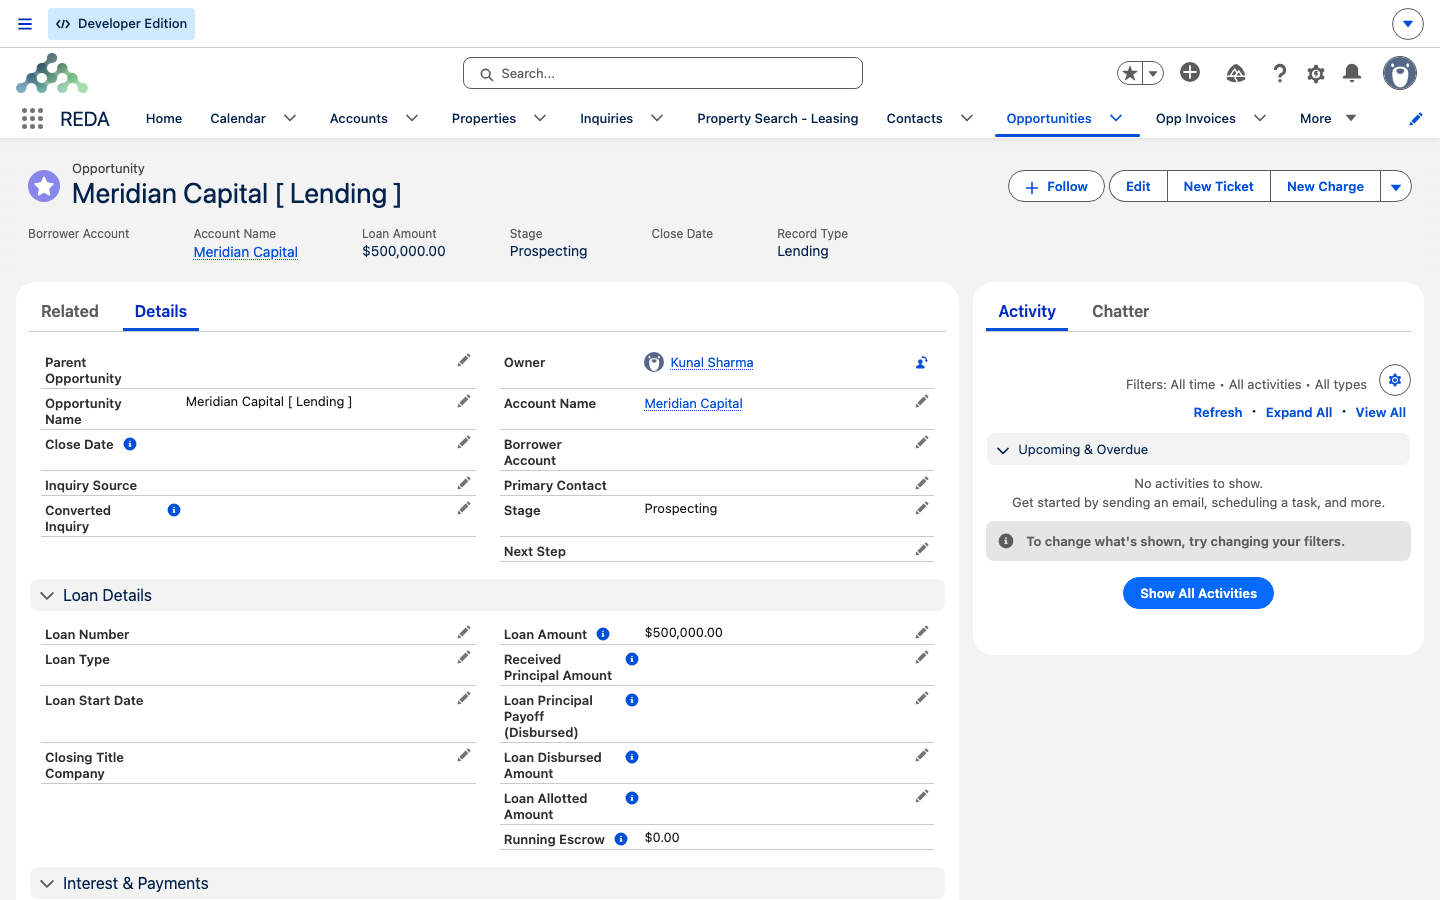
Reference: the terms block
One row per term field, and whether REDA computes anything from it. The short answer, for the terms that describe repayment, is no — they are documentation.
| Field | What it records | Does REDA compute from it? |
|---|---|---|
| Loan Amount | The principal ceiling | Caps and rollups only — no schedule |
| Loan Number | An external lender reference | No |
| Loan Type | Private / Bank / Institutional / Internal / Equity / Allocation | Allocation is restricted to child loans |
| Loan Start Date | The term start of record | No |
| Amortize | Interest Only / Amortize | No — documentation only |
| Frequency | Annually / Monthly / Quarterly | No — documentation only |
| Interest Rate | The annual rate of record | No — interest is entered per payment |
| Interest Accrual Type | Arrears / Advance | No — documentation only |
A quick guide to the loan types: Private, Bank, and Institutional are external lenders; Internal is your own entity lending to itself; Equity is investor equity tracked as a loan; Allocation is a child slice of a parent facility.
Reference: the rules REDA enforces
These are the checks you may meet while setting up or servicing a loan, quoted exactly as REDA shows them.
| When | Message |
|---|---|
| Borrower differs from the acquisition's buying account | "Borrower Account must be same as Buying Account on Acquisition Opportunity." |
| Property differs from the acquisition's property | "Property must be same as on Acquisition Opportunity." |
| A child's account differs from the parent's borrower | "On Lending Opportunity if "Parent Opportunity" is not blank and "Account" is not blank, then Account must be same as Borrower Account on Parent Opportunity." |
| Allocation type chosen on a loan with no parent | "The Loan Type Allocation option is only available for child lending opportunities." |
| Allotted total would exceed the parent's Loan Amount | "Allotted Amount must be less than Loan Amount" |
| Disbursed money would exceed the Loan Amount | "Disbursed Amount must be less or equal to Loan Amount." |
| Received principal would exceed the Loan Amount | "Received Principal Amount must be less or equal to Loan Amount." |
Where to go next
- Loan Terms & Allocation — fill in the terms block and split a facility into child loans.
- Recording Loan Payments — log the money moving on a loan, one row at a time.
- The Loan Repayment Schedule — build and read a loan's schedule of instalments.
- Escrow & Principal Balances — every balance figure on the loan, explained in words.
- Property & Acquisition Loan Rollups — how a loan's numbers surface on the property.
- Disbursements & Payoffs — the tickets that draw funds and retire a loan.
Frequently asked questions
No. The terms fields — Interest Rate, Amortize, Frequency, Accrual — are the record of the agreement, not inputs to a calculator. REDA builds no schedule and computes no interest. You create a Loan Payment row for each instalment, entering the principal and interest split you calculated yourself.
Allocation is reserved for child loans. REDA responds: "The Loan Type Allocation option is only available for child lending opportunities." Set a Parent Opportunity first, or choose a different loan type.
Each is capped by the Loan Amount. You'll see one of: "Allotted Amount must be less than Loan Amount", "Disbursed Amount must be less or equal to Loan Amount.", or "Received Principal Amount must be less or equal to Loan Amount." Raise the Loan Amount first if the loan was genuinely upsized.
When a loan is linked to an acquisition, it must fund that acquisition's purchase. So the borrower must be the acquisition's buying account and the property must match: "Borrower Account must be same as Buying Account on Acquisition Opportunity." and "Property must be same as on Acquisition Opportunity."
No. Every property born from an acquisition gets a placeholder Lending deal named TBD, opened at Prospecting, so the financing you expect to arrange has a home. Fill it in with the real lender and terms rather than deleting it.
When it becomes active — Funded, Closed Won, or Payoff Pending. A loan at Prospecting or Pending is still just a plan and moves no totals.
Was this article helpful?